
Telco Infrastructure Vendors Need to Diversify to Remain Relevant
 By Dimitris Mavrakis |
07 Oct 2026 |
IN-8295
Log In to unlock this content.
You have x unlocks remaining.
This content falls outside of your subscription, but you may view up to five pieces of premium content outside of your subscription each month
You have x unlocks remaining.
By Dimitris Mavrakis |
07 Oct 2026 |
IN-8295
NEWSTelco Vendors Start to Diversify Beyond Network Infrastructure |
This summer’s financial results show all four large infrastructure vendors growing beyond their main client base—telco network operators—at very different paces.
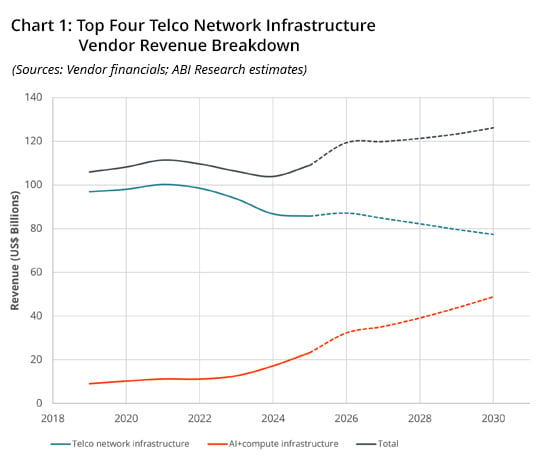
According to company financials and ABI Research estimates, vendor revenue breaks down as follows: Nokia's net sales rose 8% to €4.82 billion in 2Q, and comparable operating profit rose 18% to €434 million, driven by companies building Artificial Intelligence (AI) data centers. Orders from AI and cloud customers reached €2.8 billion. On a reported basis, however, restructuring charges pushed it to a €50 million operating loss. ZTE's computing business grew to an impressive 35.1% of revenue, but ZTE says the shift in mix is squeezing gross margins. Ericsson is diversifying within connectivity instead with its enterprise segment adjusted loss widening to SEK 0.8 billion, while annual recurring patent-licensing revenue reached about SEK 13.5 billion. Huawei is diversifying most broadly and at the highest cost. 1H revenue rose 9.6% to CNY 467.82 billion, but net profit fell about 37%, as Research and Development (R&D) jumped 25.2% to CNY 121.38 billion, or 25.9% of revenue. That spending is going into AI chips, cars, devices and computing. Chart 1 illustrates historical revenue, broken down by subsegments using ABI Research assumptions where necessary.
IMPACTAll Vendors Need to Diversify, Now |
It is now becoming clear that vendors need to diversify to survive, for many reasons:
- 6G will likely start ramping up after 2030 and slower than 5G. Mobile network operators illustrate investment fatigue from nationwide 5G rollouts and have not yet monetized 5G extensively with enterprise use cases.
- The broader geopolitical environment is uncertain, causing additional investment reluctance.
- AI has become the dominant technology investment cycle, pulling capital, investor attention, and supplier priority away from telco infrastructure.
- Custom silicon may no longer be the dominant differentiator for radio infrastructure as NVIDIA’s AI-RAN initiative aims to introduce Commercial Off-the-Shelf (COTS) processors into the Radio Access Network (RAN). Operators are cautious about the move away from custom silicon and large vendors have different positions, but NVIDIA’s push into the market has momentum.
Vendors need to diversify to survive, but only selling into AI data centers is paying off at scale so far as the enterprise sector remains a loss-maker for most vendors and has not reached significant scale. Existing diversification initiatives are ongoing but affecting vendor margins because diversification requires upfront investment. For example, ZTE noted that the changing revenue mix and industry transition is putting pressure on gross margins, which is in line with its strategic transition to a more diversified portfolio. Huawei is the obvious outlier, with sanctions that forced it to focus on China, build its own AI chips, and now becoming a major AI infrastructure provider in China. Other large vendors cannot hope to match this, but even Huawei’s profits show that this approach is expensive to maintain.
Ericsson’s strategy to remain out of AI, data center infrastructure, and interconnect businesses is logical given its expertise and market position, but its current diversifiers are too small and depend on telcos. Moreover, Borje Ekholm, the current Chief Executive Officer (CEO) is currently being replaced by Per Narvinger who was previously Head of Networks at the Swedish vendor so it is likely the vendor will remain focused on its existing client base and not branch out to data centers. As far as Ericsson’s strategy is concerned, the vendor has reiterated its focus on AI voice and Application Programming Interfaces (APIs) for telco networks, as well as developing its own AI neural processors for RAN.
There is also a risk of neglecting the core telco business. As data center and computing infrastructure revenue grows, they will likely take a larger share of R&D and management attention. This is now becoming clear in financial results and The 3rd Generation Partnership Project (3GPP), where initial ABI Research analysis indicates that large vendors are dedicating fewer resources for chairmen and rapporteurs compared to previous years, during the intense rollout of 5G networks. In fact, recent 3GPP analysis indicates lower participation of Chinese vendors, but higher participation of Chinese operators.
RECOMMENDATIONSVendors Should Diversify and Prepare for the Distributed AI Inference Opportunity |
Discussions in 3GPP and the broader industry indicate that new generations of telco networks will converge with AI infrastructure, and telcos are the ideal partner to offer sovereign AI, and localized and secure AI services. Certain operators are already moving to capture this market, including DT, SK Telecom, and SoftBank having already deployed Graphics Processing Units (GPUs) and offering them to enterprises. Most AI inference workloads will likely run in hyperscaler data centers, and the telco role is narrower: addressing lower latency use cases and applications, and data kept in-country or in proximity to devices, including Physical AI applications. At some point, there will need to be orchestration between the AI and network domains, and vendors should prepare to become the right partner for telcos to transform to AI platform providers with this orchestration capability as a key differentiator.
In the meantime, diversification should not starve the telecoms industry business, which still funds a large share of R&D and is still very important for operator trust. Nevertheless, it remains to be seen whether 6G revenue will justify the effort and investment needed to participate in 3GPP and what effect this will have in patent creation and, ultimately, licensing strategies. Their unique assets and expertise, including carrier-grade reliability, security accreditation, and sovereign supply credentials, must anchor offers for sovereign and regulated AI inference, where telcos can outcompete global cloud providers. Finally, vendors should experiment with alternative business models, including co-selling with operators instead of bypassing them, using revenue-sharing and managed-service models.
Written by Dimitris Mavrakis
- Competitive & Market Intelligence
- Executive & C-Suite
- Marketing
- Product Strategy
- Startup Leader & Founder
- Users & Implementers
Job Role
- Telco & Communications
- Hyperscalers
- Industrial & Manufacturing
- Semiconductor
- Supply Chain
- Industry & Trade Organizations
Industry
Services
Spotlights
5G, Cloud & Networks
- 5G Devices, Smartphones & Wearables
- 5G, 6G & Open RAN
- Data Centers
- Enterprise Connectivity
- Space Technologies & Innovation
- Telco AI
AI & Robotics
Automotive
Bluetooth, Wi-Fi & Short Range Wireless
Cyber & Digital Security
- Citizen Digital Identity
- Digital Payment Technologies
- eSIM & SIM Solutions
- Quantum Safe Technologies
- Trusted Device Solutions